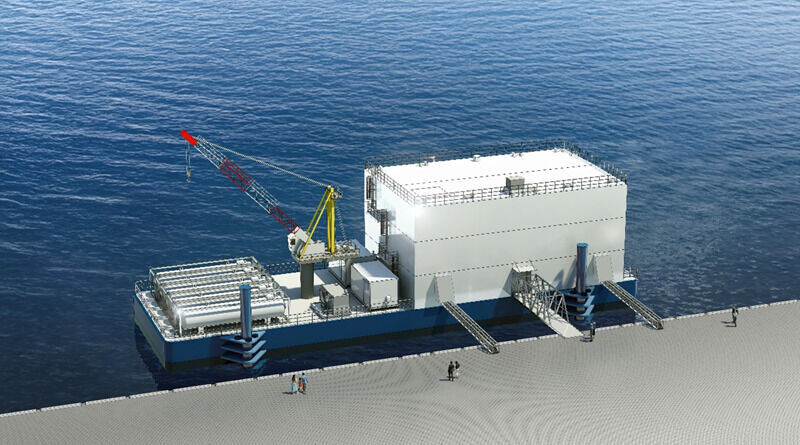
A Japanese consortium wants to ease the datacenter space crunch by putting servers afloat – but keeping them moored safely alongside port quays. The group comprises shipping and logistics corporation NYK Line, engineering biz NTT Facilities, renewable energy developer Eurus Energy, and MUFG Bank. The quartet has also considered facilities farther out at sea, where they could draw on renewable energy sources such as offshore wind. Others are exploring wave power, including Oregon-based Panthalassa. However, the fab four acknowledge that offshore deployments still face practical hurdles, including maintenance access, high-capacity telecoms links, and independent power supplies. Keeping the floating facilities alongside a quay would let them use existing port infrastructure and nearby generation while the group works toward deployments well beyond the coast. Like others eyeing the waterfront, the consortium reckons bobbing bit barns could help meet growing compute demand without competing for scarce development land, though they would still need somewhere to plug in. We asked the consortium what capacity it expects the facilities to have, and when it anticipates these might be operational, but hadn't received a response at time of publication. NYK Line will oversee development, NTT Facilities will assess the designs, construction, and operation. Eurus Energy will explore renewable power supply, and MUFG Bank will consider financing related ventures. The consortium previously signed a memorandum of understanding with the city of Yokohama for a renewable-powered demonstration at the port. Testing began in March this year. The four may find they face competition in the floating compute farm stakes. Samsung Heavy Industries plans to dip a toe in, saying it expects to have its first facility operational by the second calendar quarter of 2028. ®
AI services are unlikely to deliver enough revenue to cover the expected capital expenditure going into IT infrastructure between now and 2030, and it looks like neocloud operators will largely bow out or be bought out. This is the conclusion from Gartner, which has added up the anticipated investments in AI datacenters over the next several years, estimated the revenue that can be expected from AI-driven applications over the same period, and found the numbers come up short. Gartner's data comes from a report, "Prepare for AI Market Consolidation: Capital Write-Downs Could Exceed $4 Trillion by 2032," which concludes that AI will not generate enough sales to profitably cover all of the planned AI capital spending before 2032 at the earliest. But forecasts typically focus on the end of the decade, so it ran the numbers for 2030 as well. "In 2026, AI providers are expected to spend nearly $1 trillion on AI infrastructure, and are forecast to invest an additional $6 trillion between 2027 and 2030," said Gartner senior director analyst Will Sommer. "However, our research indicates that enterprise and consumer AI revenue will be insufficient to support profitable returns on all planned AI capital expenditures during this period." Assuming a 12 percent return on invested capital (ROIC), which many companies are said to regard as the bar for acceptability, Gartner estimates AI datacenter operators would need to generate a total of $8.5 trillion in revenue to cover capital spending and financing costs while achieving that return. Unfortunately, it forecasts that the total enterprise and consumer AI revenue that can be attributed to AI datacenters during this period will add up to no more than $3.6 trillion. Returns below expectations could force operators to write down assets whose value they can no longer recover, particularly as newer GPUs displace older hardware. The result will be a shake-out of the companies providing AI infrastructure services, and Gartner believes that neocloud operators – "GPU-as-a-service" providers specializing in AI compute – will be the hardest hit. It forecasts that 80 percent of them won't survive as independent companies beyond 2030. "Not everyone is in trouble," Sommer told The Register. "Some will outperform, some will underperform, and some will have to exit the market." Gartner expects the hyperscalers to weather the shake-out better because their businesses extend beyond AI services. Last year, McKinsey & Company warned that neocloud companies need to move up the AI stack and diversify to avoid being commoditized. There has been growing unease in the financial markets over the amount of capex being poured into AI investment, with some money lenders starting to get cold feet. Last month, SoftBank Group found itself facing higher borrowing costs as the tech investment biz sought to drum up further funding for OpenAI. Financial biz Jefferies issued a report this week saying that developers such as OpenAI and Anthropic are facing threats to their profitability from open source and Chinese models that undercut them on price. Management consultant Bain & Company also published a report last month estimating that the AI industry needs to generate $6 trillion in annual revenue by 2031 to keep up funding for the infrastructure needed to meet anticipated demand. Bain also forecast a revenue shortfall unless the industry develops products and use cases not yet identified. Both the IMF and the Bank for International Settlements have voiced concerns about the AI bubble bursting and the effects rippling out across the global economy. ®
Datacenters are forecast to consume a growing share of Europe's electricity by 2035, potentially pushing up consumer prices and prompting governments to impose price caps or restrictions on bit barns, according to Moody's. The credit rating agency is keeping tabs on the financial implications for datacenter operators and electricity networks. It predicts that while power consumption by server farms is relatively modest today, these facilities are set to become major drivers of electricity demand by 2035, requiring utilities and network operators to invest in generation and grid capacity. Massive compute sheds still accounted for "a low single-digit share" of electricity in most of the largest European markets in 2025, typically about 2.5 percent. But some of the major markets such as the UK and France are set to see accelerating growth in the number and size of facilities that could substantially increase their share of electricity consumption. The report estimates datacenters will account for at least 5.7 percent of electricity demand in France and the UK by 2035, but could be as high as 17 percent for the Netherlands and 30 percent for Ireland. The latter country is regarded as an outlier, however, as datacenters already made up 23 percent of Ireland's electricity consumption in 2025 – up from just 5 percent in 2015. In addition, the EU has set out the goal of more than tripling the bloc's datacenter capacity within five to seven years, and wants to diversify where such projects are sited beyond the primary markets such as Germany, Ireland, France, and the Netherlands to secondary markets in the Nordics and southern Europe. This means more power generation will be needed, plus expansion of the grid networks to carry the extra energy to where it is required. Moody's says this has the potential to put pressure on grid operators' balance sheets in the short term, compounded by the lag in recovering higher capital spending under many European regulatory regimes. This pressure is more pronounced for transmission networks than distribution networks because datacenter operators are required to fund only the cost of the connection to the grid, the report by Moody's notes. It highlights some novel approaches adopted by utilities, such as repurposing old fossil-fuel plant sites for server farm projects because of their existing grid connections – as is said to be the case with at least one of the UK government's AI Growth Zones – and partnering with developers to build new facilities and supply them with power. The cost of expanding power grids, together with supply-demand imbalances, is set to push energy prices higher, Moody's forecasts. Historically, this has prompted political measures to limit the financial burden borne by customers, it says. Some governments are already considering tax cuts and additional subsidies for end users, while a growing number of transmission networks are starting to demand financial guarantees to screen out speculative or duplicative projects. The UK government is mulling over this measure, as we reported during the summer. Looking ahead, intervention could become more intrusive through measures such as electricity price caps, additional taxes, or levies. Moody's cites Ireland as an example, where the Commission for Regulation of Utilities (CRU) replaced a moratorium on new datacenter grid connections with a framework under which operators applying for a grid connection rated at 10 MVA or more must provide matching power generation or storage capacity on-site or nearby, and meet at least 80 percent of their annual electricity demand through additional renewable projects in Ireland. In America, President Trump brought in a Ratepayer Protection Pledge to try to defuse growing voter unhappiness at datacenters and their effects on energy bills. The pledge now covers utility companies, bit barn developers, and state governments with a pinky promise that citizens' bills won't rise to pay for all the extra energy and grid infrastructure needed. Moody's expects more European governments to follow the US and Ireland in intervening over datacenter power demand if expansion continues on its current trajectory. ®

 Accedi